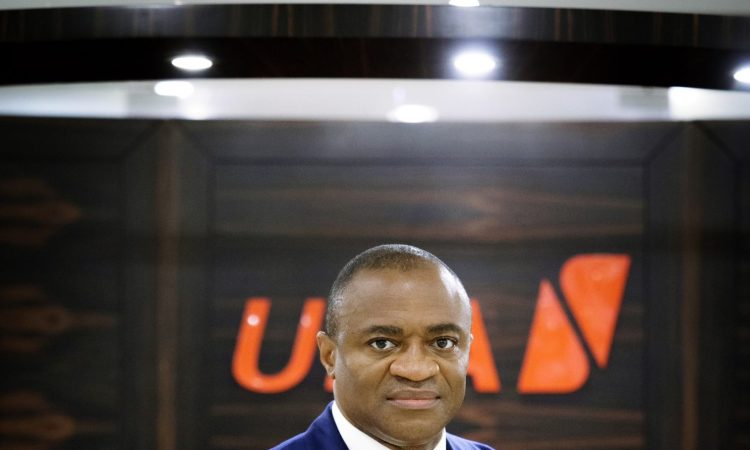

UBA’s Group MD on bank recapitalisation, digital investment and why sector resilience must translate into real opportunity for Nigerians
By Angeline Mgbele, Bureau Chief, Northern Nigeria and Kingsley I. Ilechukwu, Bureau Chief, South West, Nigeria
Group Managing Director of United Bank for Africa and Chairman of the Body of Bank CEOs in Nigeria, Oliver Alawuba, has outlined a blueprint for building a resilient Nigerian economy, calling for deliberate policies and stronger collaboration across the public and private sectors to transform economic stability into inclusive prosperity.
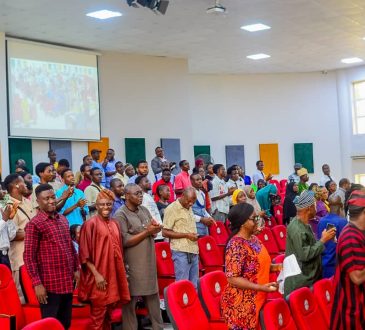
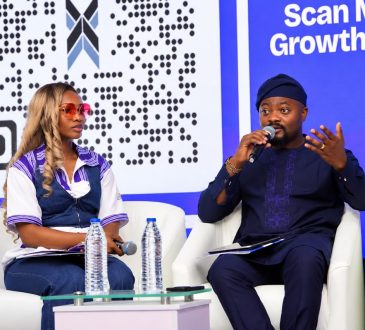
Alawuba made the call while delivering his goodwill speech at the 19th Annual Banking and Finance Conference of the Chartered Institute of Bankers of Nigeria (CIBN), held in Abuja on Tuesday, September 8, 2026.
Speaking on the theme of the conference, “Building a Resilient Economy in an Era of Disruptions: Imperatives for the Banking and Financial Services Industry,” Alawuba said resilience must be deliberately designed into Nigeria’s policies, institutions, infrastructure, supply chains, energy systems, financial architecture and human capital.
According to Mr. Alawuba, a resilient economy was not one that never encountered shocks, but one that could absorb, adapt and advance without transferring the full cost of every disruption to its most vulnerable citizens.
Alawuba noted that the global economy continued to face structural disruptions, from geopolitical conflicts and volatility in energy and shipping markets to inflationary pressures, making it imperative for Nigeria to build systems capable of withstanding future shocks rather than responding only after they occured.
Alawuba commended the Federal Government and the Central Bank of Nigeria (CBN) for the increasingly effective coordination between fiscal and monetary policy, noting that recent improvements in key economic indicators provided important milestones in Nigeria’s stabilisation journey.
He also stressed that these gains must now be translated into broader economic opportunities and improved living standards and further highlighted the critical role of the banking industry in Nigeria’s resilience agenda, describing banks as the country’s “financial shock absorbers and growth partners.”
The UBA boss, pointed to the ₦4.65 trillion mobilised by 33 banks during the recent recapitalisation exercise as a significant step towards strengthening capital adequacy, asset quality, balance-sheet transparency and investor confidence, while expanding the industry’s capacity to absorb shocks and finance larger projects.
According to Alawuba, the banking sector’s resilience was being reinforced by accelerated investment in digital infrastructure, cybersecurity and operational resilience, citing technology investments of over ₦119 billion by four leading banks in the first quarter of 2026, representing a 43.2 per cent year-on-year increase.
During the event, President Bola Ahmed Tinubu, represented by the Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, challenged the banking industry to move beyond balance-sheet expansion and profitability to financing productive businesses that could drive investment, job creation and economic growth.
President Tinubu said the next phase of Nigeria’s reform journey must focus on moving from financial intermediation to economic transformation, with affordable credit, financial inclusion, technology and long-term capital identified as key drivers of a more resilient financial system.
Also speaking at the conference, CBN Governor, Olayemi Cardoso, represented by the Deputy Governor, Economic Policy Directorate, Philip Ikeazor, reaffirmed the importance of a strong banking sector to sustaining Nigeria’s economic recovery, while World Bank Country Director for Nigeria, Mathew Verghis, called on banks to redirect more capital towards businesses capable of creating jobs.
President/Chairman of Council of CIBN, Dr. Dele Alabi, also stressed that the ultimate test of Nigeria’s economic reforms would be whether improved macroeconomic indicators translated into lower living costs, more jobs, higher incomes and affordable credit for citizens and businesses.
In his concluding remarks, Alawuba reaffirmed the banking industry’s readiness to work with the Federal Government and urged stakeholders to ensure that the resilience being built within the financial sector ultimately translated into tangible economic opportunities and a more prosperous future for Nigerians.